

Tribune of Diego Azqueta Smith, Director of International Origination of BIORIG, in El Español
Biomethane has established itself as one of the key energy carriers in the European Union. This is no coincidence: it is a locally produced, sustainable energy source that is compatible with existing natural gas infrastructures.
Its mass deployment is no longer an idea for the future, but an institutional priority. The European Union, through the Commission, has set a target of achieving an annual production of 35 bcm of biomethane by 2030 – approximately 10.5% of European consumption.
The reasons for this determined gamble are not only environmental, but also geopolitical: in less than two years, the EU must find an alternative to Russian gas imports, which accounted for around 18% of the continent’s gas purchases in 2024; in line with the plan to completely eliminate energy purchases from Russia by 2027.
Energy security has led Italy to make biomethane a strategic priority.
The destination set by Brussels is clear, and the ball is now in the court of the Member States, which have to build the paths to be followed by the different actors involved in the deployment of biomethane (producers, consumers, the primary sector, local administrations, etc.).
However, this deployment is uneven, and while some countries are following this development in the fast lane, on well-marked and direct roads, others are moving forward on curvy roads with diffuse signage and uneven surfaces.
Untapped potential
Spain has already taken up the European baton through the latest update of the National Integrated Energy and Climate Plan (PNIEC), which sets a target of 20 TWh of biogas by 2030, of which approximately 12 TWh is expected to come from biomethane.
Biomethane is a renewable energy and molecularly identical to fossil natural gas, allowing it to be stored, transported and injected into the current grid.
The Italian government has already started to redirect planned aid from hydrogen to biomethane.
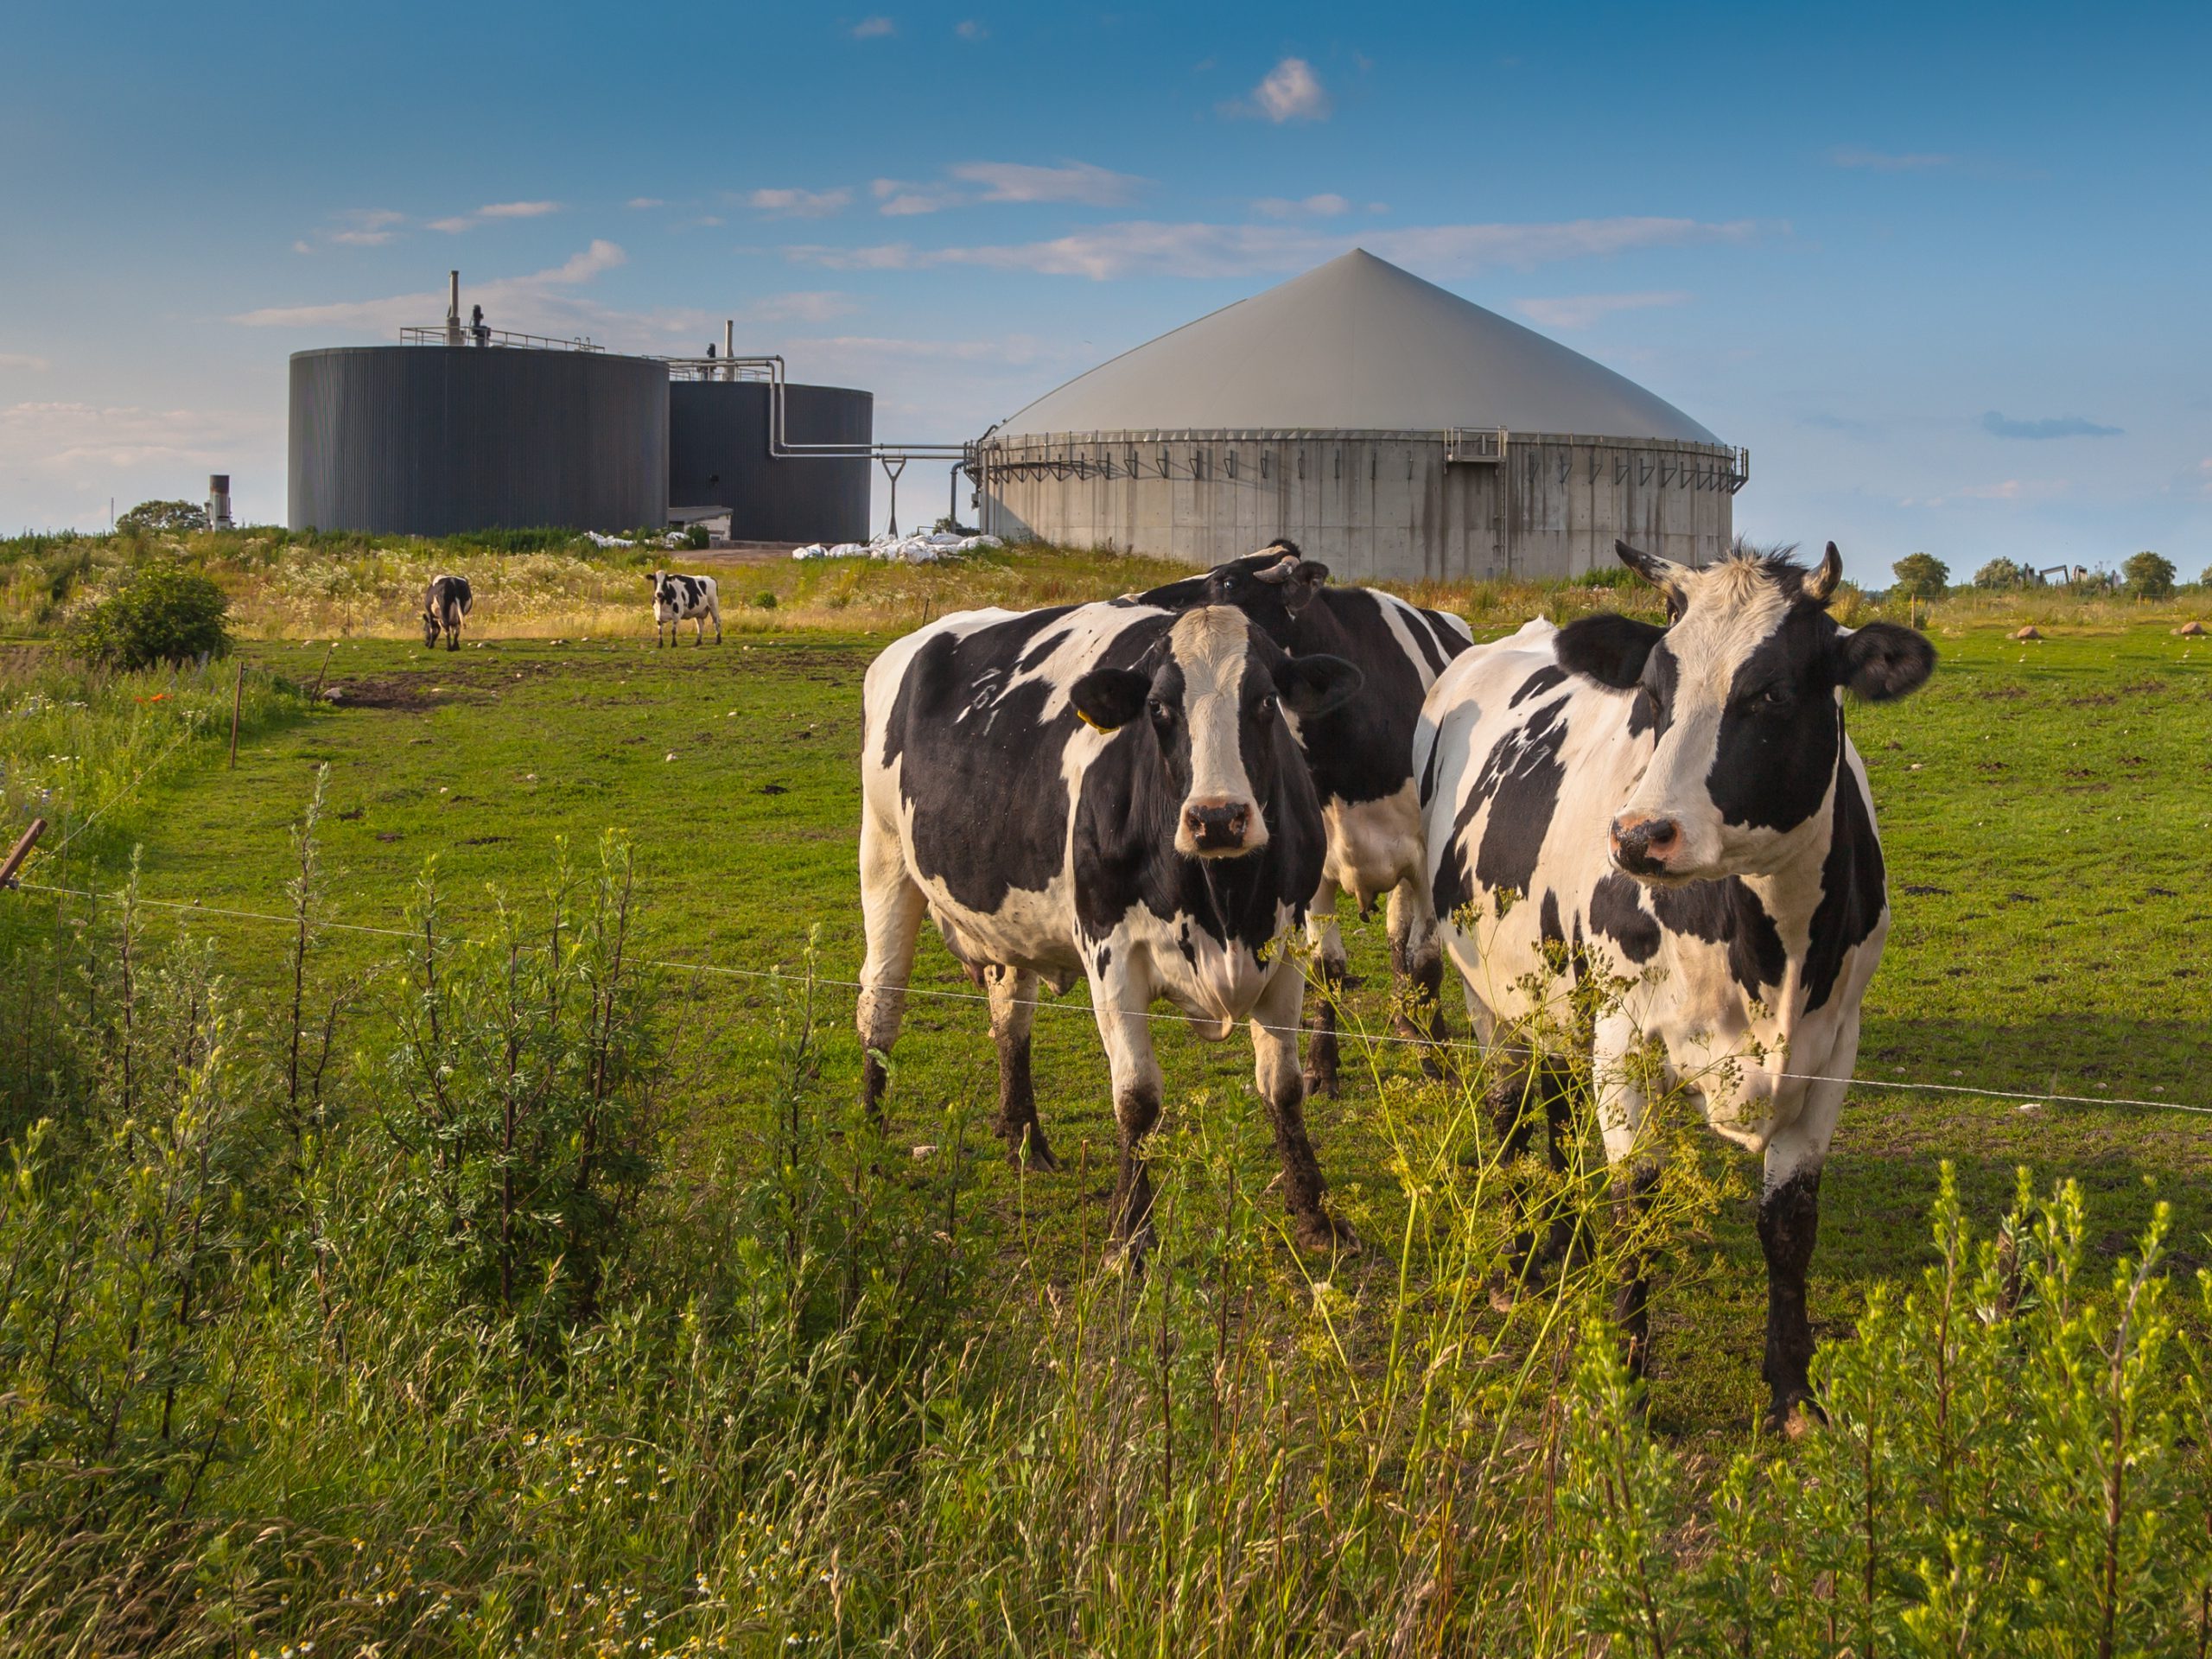
It is a mature technology that offers a viable solution for sectors that are difficult to electrify, such as heavy transport or industry. Moreover, it is produced using “kilometre 0” raw materials, such as organic agricultural and livestock waste – slurry and manure – which solves the challenge of the correct environmental management of waste from the primary sector.
In Spain, the opportunity is enormous. According to Sedigas, we are the third European country with the greatest potential and we have the capacity to generate up to 163 TWh/year, more than half of the national consumption of fossil natural gas.
The Italian case
However, potential does not guarantee success. Italy shows that, with the right stimulus, it can lead the sector in Europe. Despite ranking fifth in Europe in terms of the volume of raw materials available, it has built a functional, scalable and territorially integrated industry from scratch in record time.
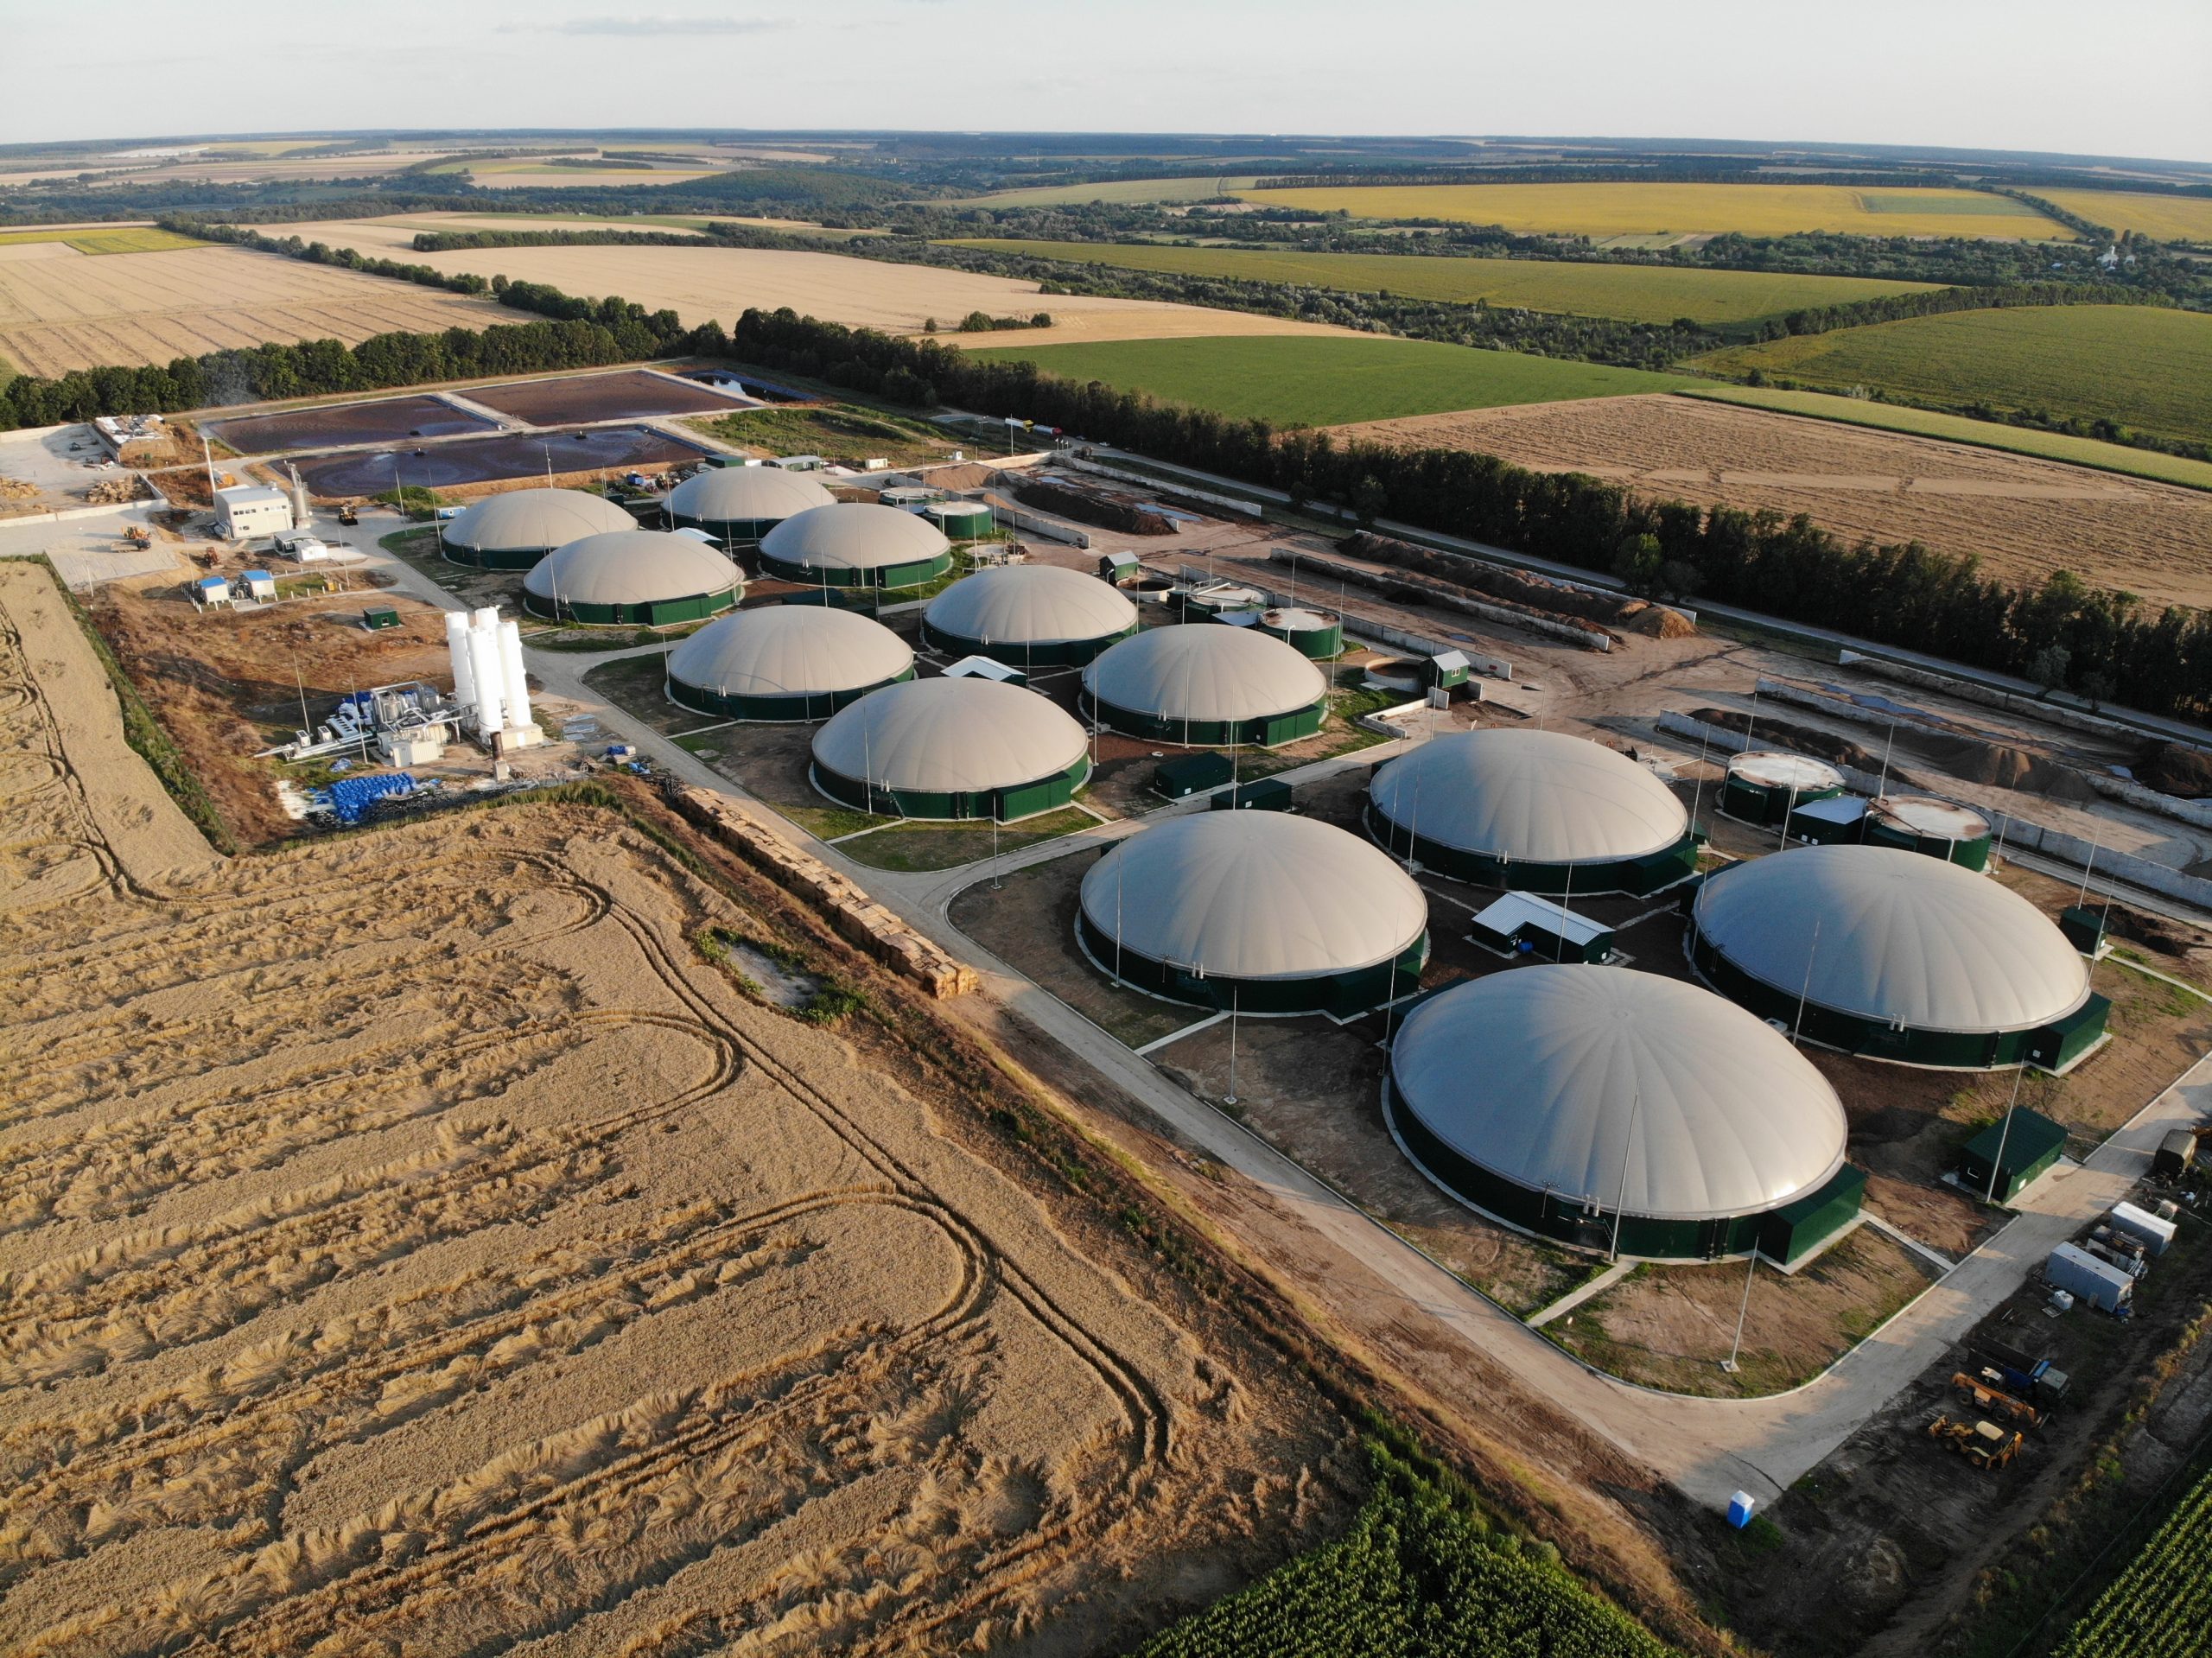
Just look at the figures: in 2018, Italy had only seven installations connected to the gas grid. Spain, on the other hand, had just one. By the end of 2024, the leap is clear. Italy has 133 plants in operation, 101 of which were commissioned in the same year. Spain, on the other hand, only had 9 plants in operation.
One of the keys to Italy’s acceleration has been urgency. In 2024, 44.1% of its energy production came from natural gas, much of it still imported from Russia. In contrast, Spain has reduced this dependence to 18.7% thanks to renewables, although it still needs to diversify its energy mix.
Energy security has led Italy to make biomethane a strategic priority.
This has favoured a strong and coherent institutional support framework, including investment grants, volume bonuses and feed-in tariffs, which guarantee a fixed price for a fixed period of time, reducing the financial risk of projects.
Many of these grants are financed by Next Generation EU funds and expire in the first half of 2026. To keep pace, Italy needs new incentives.
The government has already started to redirect planned hydrogen subsidies towards biomethane, adding 640 million euros to the fossil gas substitution effort. But to reach the 5.7 bcm (55 TWh/year) target set in the Italian PNIEC for 2030, it will be necessary to look beyond the short term.
Rural development and the circular economy
In Spain, on the other hand, the focus has been on supply. Current aid, which is scarce and limited in volume, is focused on reducing the cost of building plants, but without articulating a solid demand that would encourage production.
This imbalance could result in energy produced in Spain being exported to countries with better demand conditions, losing an opportunity for reindustrialisation, boosting local development and ecological transition.
To consolidate the sector, Spain needs to move towards a demand-side support scheme that guarantees the viability of projects.
Today, biomethane is more expensive to produce than fossil gas, so it needs incentives to compensate for this difference and optimise its benefits. These go far beyond the decarbonisation of the energy sector, as biomethane also contributes to the generation of a circular economy in agricultural environments, helps bring investment to rural environments and ensures energy sovereignty with a renewable gas made from local inputs.
At Biorig we believe that Spain not only has the potential to lead this transformation, it has the experience, the environmental commitment and the business fabric to make it happen. Italy has shown that it is possible. Now it is Spain’s turn to make biomethane a shared success story between the countryside and industry.